Filing Alert: Air Baltic Chapter 11
Air Baltic Files Chapter 11 in Southern District of New York
Update (September 15, 2026): A comprehensive case summary is now available for the Chapter 11 bankruptcy filing of Air Baltic Corporation AS.
Air Baltic Corporation AS and its debtor affiliates⁽¹⁾, a Mārupe, Latvia-based flag carrier airline, filed for Chapter 11 protection on Sep. 14 in the U.S. Bankruptcy Court for the Southern District of New York.
The Debtors attribute the filing to macroeconomic and operational shocks compounding over six years, on top of leverage incurred to fund a pre-pandemic growth plan. That plan, built around a single-type A220-300 fleet, was financed in part by a $232.0 million bond issued in 2019. In 2024 the Debtors issued the 14.500% senior secured bonds due 2029 (the "2029 Bonds"), in part to refinance that bond. As of the Petition Date, approximately $456.8 million in principal amount of the 2029 Bonds remained outstanding. The Debtors enter Chapter 11 with approximately $583.9 million of funded debt and approximately $992.5 million of operating lease obligations.
As a result of the COVID-19 pandemic, the Debtors incurred approximately $527.8 million of losses from 2020 through 2022 and needed substantial state support to survive. The Latvian government provided $290.0 million of emergency equity in July 2020 and a further $104.4 million recapitalization across 2021 and 2022, lifting its ownership to approximately 97.97%.
Just as the Company was recovering from the pandemic, two further disruptions constrained its network and fleet. Russia's 2022 invasion of Ukraine forced the permanent suspension of Russian, Belarusian, and Ukrainian routes and required longer, costlier routings. Suspending the Russia and Ukraine flights alone reduced 2022 passenger revenue by an estimated $46.4 million. At the same time, beginning in 2022, a shortage of spare Pratt & Whitney PW1500G engines, the only engine certified for the A220-300, kept aircraft out of service. The Debtors had an average of 8.0 and 7.7 aircraft on the ground during the 2024 and 2025 summer seasons, and quarterly averages reached as high as thirteen. The groundings led to flight cancellations and reduced operating margins. They also required the Debtors to source costly aircraft, crew, maintenance, and insurance ("ACMI") services from other operators.
The proximate cause of the filing was the 2026 jet fuel shock. Fuel has historically represented approximately 20–27% of total operating expenses, and the Debtors, approximately 90% unhedged, entered 2026 assuming a price of approximately $685 per ton. After the outbreak of the Middle East conflict, prices peaked near $2,000 per ton, approximately 109% above January 2026 levels. They averaged $1,168 per ton over the first eight months of the year, $454 above the prior-year period. In March 2026 the Debtors sold their remaining hedges for approximately $6.6 million to avoid defaulting on the Minimum Liquidity Requirement covenant under the 2029 Bonds. That left them fully exposed to spot prices for April through December 2026, when each $100 per ton increase adds approximately $16.5 million of cost. The market reaction was severe: the 2029 Bonds fell from the mid-93s in late January 2026 to the 20s by August, foreclosing any realistic out-of-court refinancing.
The Debtors' planned equity solution did not arrive in time. A planned IPO on Nasdaq Riga and the Frankfurt Stock Exchange, targeting an estimated $290.0 million primary raise, was repeatedly delayed as European airline share prices declined and the Debtors' performance could not support the required valuations. In April 2026 the government of Latvia bridged the gap with a $34.8 million subordinated emergency loan. Using that time, the Debtors retained Seabury Securities LLC and Milbank LLP and formulated a revised business plan (the "Business Plan"). Executing the Business Plan required a significant liquidity infusion and a balance sheet recapitalization. It also required consents from lessors, bondholders, and other counterparties that could not be obtained before late 2026 at the earliest, so the Debtors needed interim financing to reach that point.
The search for interim financing ran through the summer of 2026. A solicitation drew term sheets from four providers, including an ad hoc group of 2029 bondholders (the "Ad Hoc Group"). Talks with third-party providers stalled because a significant portion of the Debtors' assets was already encumbered in favor of the bondholders, and no party would lend other than on a super-senior basis requiring bondholder consent. The Debtors therefore turned to the Ad Hoc Group. They proposed $261.0 million of interim financing, $261.0 million of new long-term debt, $116.0 million of fresh equity, and a partial equitization of the 2029 Bonds with take-back debt of up to $145.0 million. To preserve liquidity while that framework was negotiated, bondholders approved on Aug. 17, 2026 converting the Aug. 14 and Nov. 14, 2026 cash coupons to PIK and suspending the $29.0 million minimum liquidity covenant. Negotiations proved protracted, however. When fuel prices rose again in late summer, it became evident that the Ad Hoc Group proposal likely would not provide sufficient liquidity, and the Debtors solicited bids for approximately $406.0 million of DIP financing.
Through the Chapter 11 Cases, the Debtors intend to implement the Business Plan. That means returning approximately twenty surplus aircraft, obtaining reduced lease rates, reprofiling the remaining lease obligations, and addressing outstanding obligations in an orderly fashion while preserving the core route network and employee base. The Business Plan targets a fleet of thirty-six aircraft by year-end 2026, down from fifty-four, and approximately forty by 2031, along with approximately $52.2 million of annual operating cost savings. It also contemplates the cancellation or indefinite deferral of forty firm A220-300 orders, which carry a list-price commitment in excess of $3.5 billion, and of approximately $106.7 million of undelivered Pratt & Whitney engines. To that end, the Debtors aim to reach consensual agreements with lessors and OEMs and to obtain commitments for exit debt and equity financing.
A DIP facility will fund operations through the case. On Sept. 12, 2026, after a marketing process with multiple bidders, including the Ad Hoc Group's interim proposal, the Debtors signed a commitment letter for a $406.0 million facility. It is a new-money, superpriority senior secured term loan from Barclays, Hayfin Capital Management, Morgan Stanley, Oaktree Capital, and Strategic Value Partners. Of that amount, $203.0 million becomes available on entry of the interim order, with the balance in two tranches on entry of the final order. Beyond funding operations, proceeds will be used to exercise the purchase option under the finance leases and to repay the existing debt on the financed equipment.
Air Baltic Corporation AS reports $1 billion to $10 billion in both assets and liabilities. The filing indicates that there will be funds available for distribution to unsecured creditors. The case number is 26-12188.
⁽¹⁾ Air Baltic Training, SIA and Baltijas Kravu Centrs SIA.
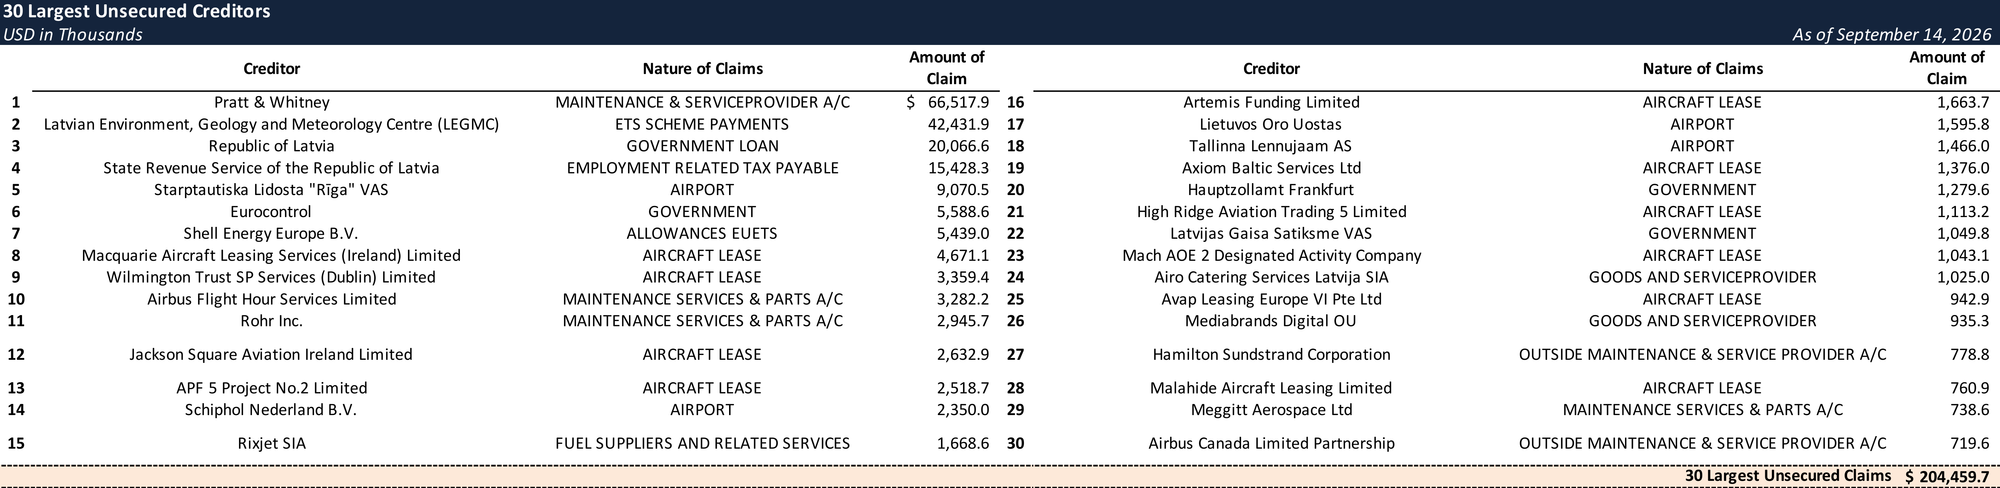
Top Unsecured Claims
Key Parties
General Bankruptcy Counsel:
- Evan R. Fleck
Milbank LLP
Email: EFleck@milbank.com
Corporate Co-counsel:
- Cobalt Latvia
- Clyde and Co
Investment Banker:
- Seabury Securities LLC
Claims Agent:
- Epiq Corporate Restructuring, LLC
Signatories:
- Vitolds Jakovļevs – Authorized Signatory
Equity Security Holders:
- Republic of Latvia (Ministry of Transport) – 88.37% Equity Interest
- Deutsche Lufthansa AG – 10% Equity Interest
- Aircraft Leasing 1, SIA – 1.62% Equity Interest
- Frontier Enterprises SIA – <0.01%
- OJSC Transaero Airlines – <0.01%
- Redacted – <0.01%
Bondoro Insights is continuing to monitor this case and will provide further coverage as appropriate.
Stay informed on every Chapter 11 bankruptcy case with liabilities exceeding $10 million. Subscribe for free to have our coverage delivered directly to your inbox, and explore our full archive of past summaries.
Explore Bondoro Insights for live case dockets and comprehensive coverage of material filings from petition to plan confirmation.


