Case Summary: Brightline Chapter 11
Brightline's holding companies filed Chapter 11, keeping the Miami–Orlando railroad out of court. An RSA with Assured and mutual funds would fund it and leave muni principal intact; the main Parent Notes group isn't a party. The Debtors cite heavy leverage and below-forecast ridership and fares.

A deck version of this summary is also available HERE.
Business Description
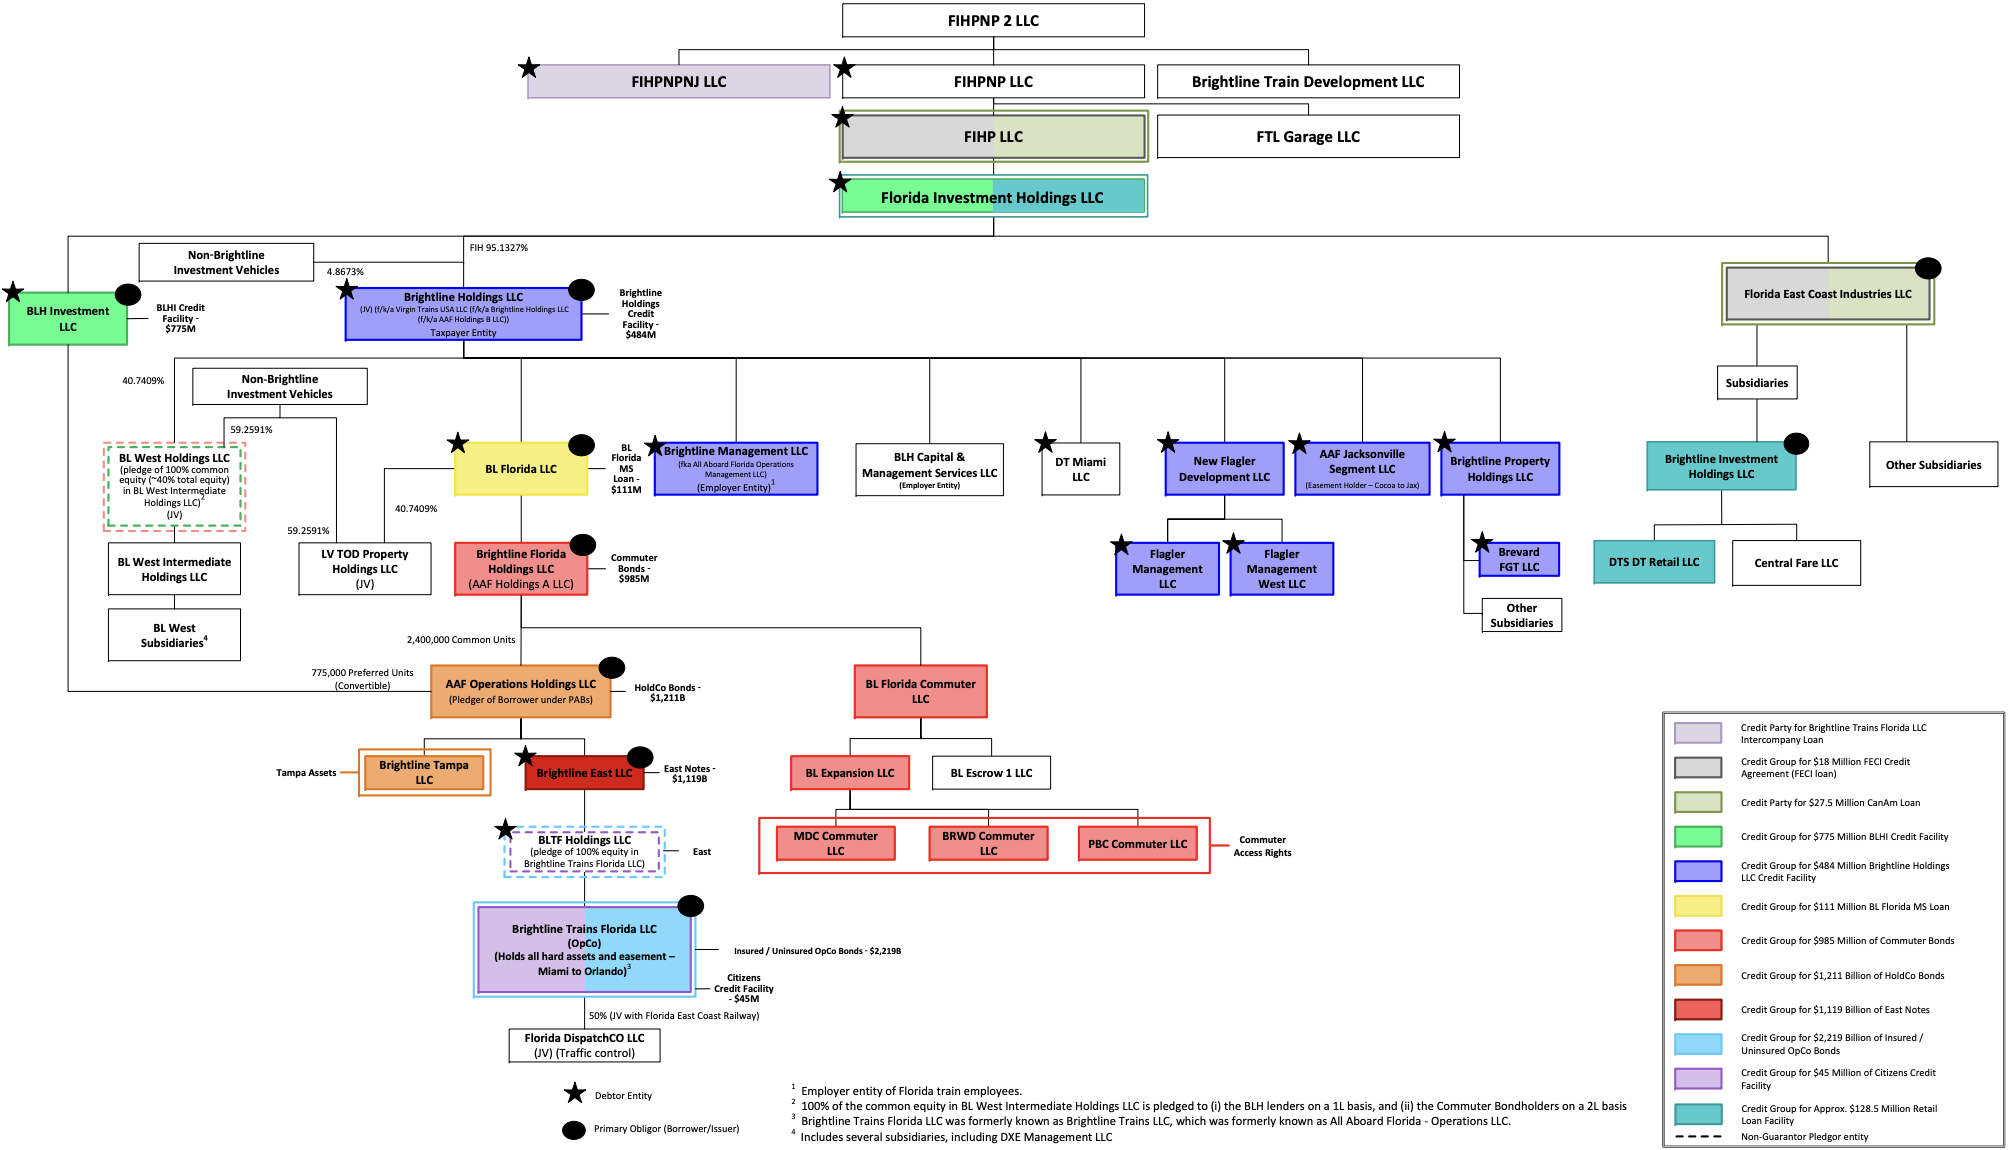
Headquartered in Miami, FIHPNP LLC ("FIHPNP") and its Debtor affiliates (collectively, the "Debtors"), 17 entities in all, are holding companies whose primary assets include their direct and indirect ownership of non-Debtor Brightline Trains Florida LLC ("OpCo"). The Debtors and FIHPNP's wholly owned or controlled non-Debtor subsidiaries together make up the "Company."
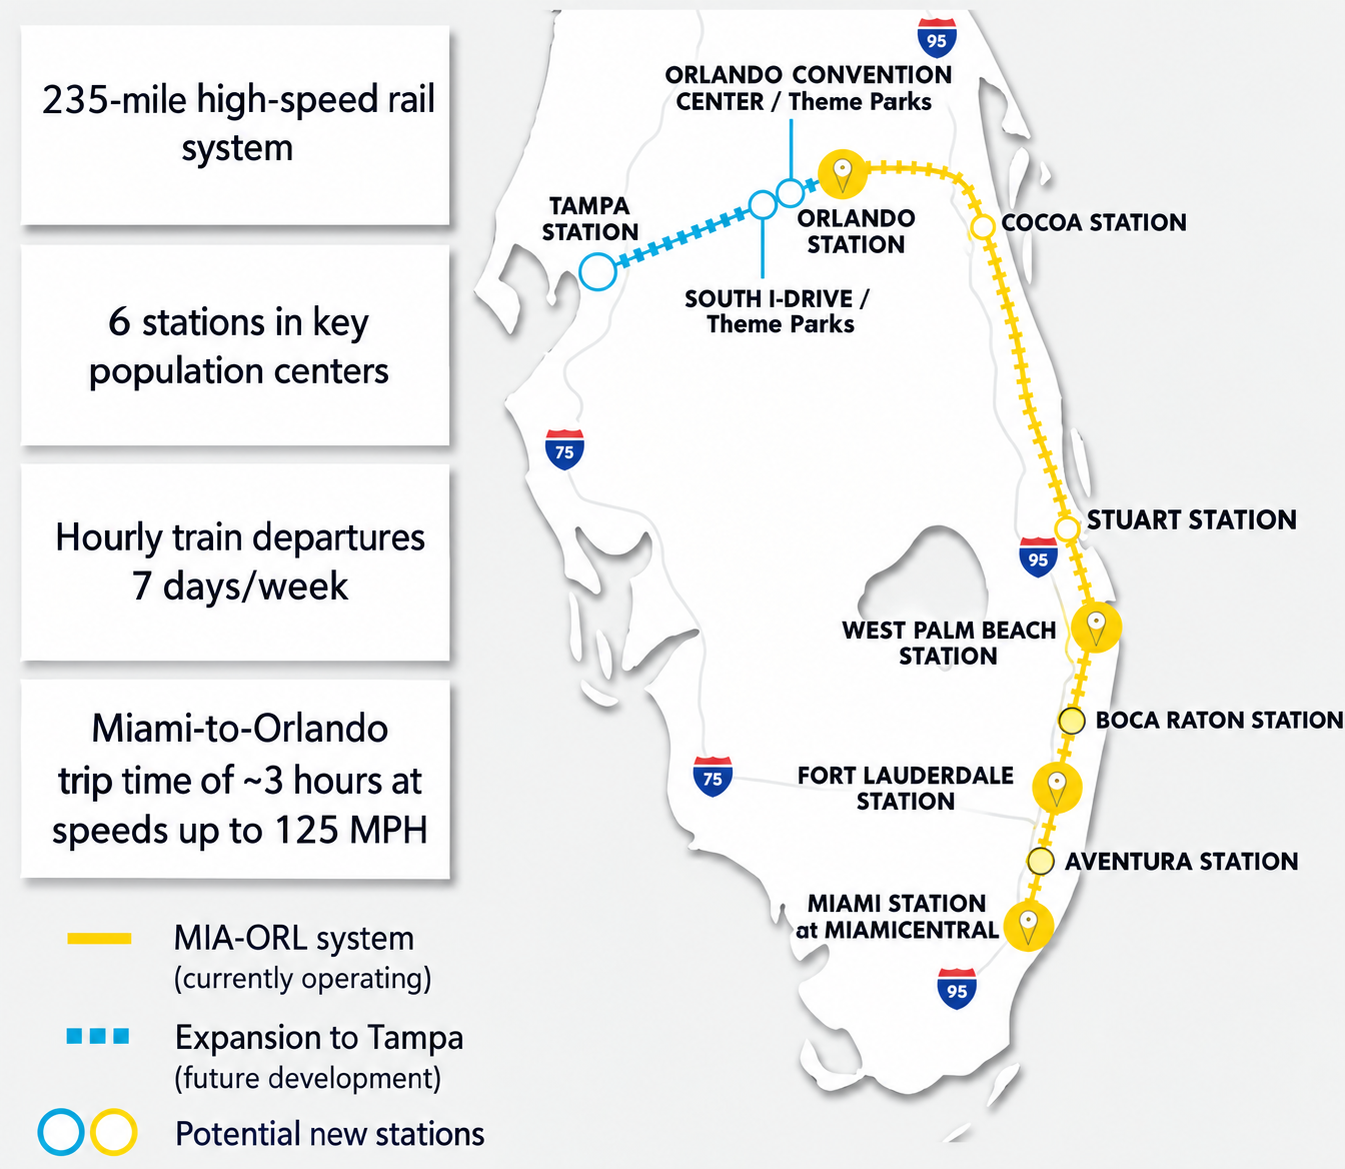
OpCo, a non-Debtor, operates the roughly 235-mile intercity passenger rail system between Miami and Orlando (the "Rail System") and runs up to 36 one-way trains a day serving six stations: downtown Miami, Aventura, Fort Lauderdale, Boca Raton, West Palm Beach and Orlando International Airport. For the twelve-month period ended July 31, 2026, the Rail System carried approximately 3.4 million riders and generated $234.3 million in revenue.
Beyond OpCo, the Debtors' principal assets are interests in long-term commuter rail rights along the Rail System's South Florida corridor (the "Commuter Access Rights") and in a planned Orlando–Tampa extension. The Debtors also own a non-controlling interest of approximately 40% in BL West Holdings LLC ("BL West Holdings"), an upstream holding company of Brightline West — a planned high-speed rail line between Southern California and Las Vegas.
FIHPNP LLC and certain affiliates⁽¹⁾ filed for Chapter 11 protection on September 24, 2026 (the "Petition Date") in the U.S. Bankruptcy Court for the District of New Jersey, reporting $1 billion to $10 billion in both assets and liabilities.
⁽¹⁾ For a complete list of Debtor entities, see organizational structure chart below.
Corporate History
Origins and Launch
The Company traces its history to All Aboard Florida, a Miami–Orlando passenger rail project announced in 2012 by Florida East Coast Industries ("FECI"). FECI had owned both the Florida East Coast Railway ("FECR") and the commercial real estate company Flagler Development Group. In July 2007, funds managed by affiliates of Fortress Investment Group LLC ("Fortress") acquired FECI in an all-cash deal valued at approximately $3.5 billion.
Several of today's entities date back to that project. OpCo and Debtor Brightline Management LLC ("Brightline Management") were originally formed as All Aboard Florida – Operations LLC and All Aboard Florida Operations Management LLC. Debtor Brightline Holdings LLC ("Brightline Holdings") was formed in Delaware in August 2013 as AAF Holdings B LLC and operated as Virgin Trains USA LLC from November 2018 to July 2020.
Meanwhile, in March 2017, the Fortress funds agreed to sell FECR to a Grupo México unit for a reported $2.1 billion. Entities managed by a Fortress affiliate continue to indirectly own a majority of the Debtors' equity.
Brightline began carrying passengers in January 2018 between Fort Lauderdale and West Palm Beach and extended service south to Miami that May. In September 2018, it agreed to acquire XpressWest, the developer of the project now known as Brightline West. In November 2018, OpCo won the exclusive right to develop an extension of the line from Orlando International Airport to Tampa.
Pandemic, Orlando Opening and Intercompany Transactions
In March 2020, the Company suspended all train service due to the impact of COVID-19 and to focus on developing a planned South Florida commuter rail service, resuming operations in November 2021.
Between 2022 and 2023, OpCo granted rights to run commuter trains on its South Florida tracks to other Brightline-owned companies. In February 2022, it granted rights in Miami-Dade and Broward Counties to subsidiaries of non-Debtor BL Expansion LLC for $245 million. In March 2023, it granted matching rights in Palm Beach County to subsidiaries of non-Debtor Brightline Florida Holdings LLC ("Brightline Florida") for $135 million. New stations at Boca Raton and Aventura opened in December 2022. On September 22, 2023, the Orlando station opened, completing the route between Miami and Orlando.
On January 2, 2024, OpCo sold the assets for the planned Orlando–Tampa extension to non-Debtor Brightline Tampa LLC ("Brightline Tampa"), a subsidiary of non-Debtor AAF Operations Holdings LLC ("AAFOH"), for $125 million. On April 1, 2024, it bought back certain rights needed to connect with SunRail, the Orlando-area commuter line, for $47.5 million.
Corporate Structure
- The Debtors — The 17 Debtors include Brightline Holdings, Brightline East LLC ("Brightline East"), BLH Investment LLC ("BLH Investment"), BL Florida LLC ("BL Florida") and BLTF Holdings LLC ("BLTF"), a wholly owned subsidiary of Brightline East that owns 100% of OpCo's equity. Brightline Management is the only Debtor with employees.
- Principal Non-Debtors — OpCo operates the trains, collects the ticket revenue and primarily pays its own vendors directly. The other principal non-Debtors are AAFOH, the obligor on the approximately $1.2 billion HoldCo Bonds; Brightline Florida, the obligor on the $985 million Commuter Bonds; Brightline Tampa, the AAFOH subsidiary developing the Orlando–Tampa extension; the special purpose vehicles that hold the Commuter Access Rights (the "Commuter SPVs"); and the Brightline West entities.
Operations Overview
The Rail System and Corridor Agreements
The Rail System is owned and operated by non-Debtor OpCo, which is wholly owned by Debtor BLTF, itself a wholly owned subsidiary of Debtor Brightline East. It runs on approximately 235 miles of double track: 195 miles of corridor shared with FECR between Miami and Cocoa, and about 40 miles of dedicated passenger-only track between Cocoa and Orlando.
On the Miami-Cocoa segment, OpCo holds an exclusive and perpetual passenger rail easement, FECR keeps exclusive freight rights, and corridor agreements govern shared use, including dispatching, maintenance and cost allocation. On the Cocoa-Orlando segment, OpCo holds lease and easement agreements with the Florida Department of Transportation, the Greater Orlando Aviation Authority, and the Central Florida Expressway Authority.
OpCo currently operates a fleet of ten trainsets, each consisting of two diesel-electric locomotives and multiple passenger cars. Top speeds are 125 mph between Cocoa and Orlando International Airport, 110 mph between West Palm Beach and Cocoa, and 79 mph south of West Palm Beach.
Federal Grants
OpCo's corridor is the focus of several recent federally funded projects:
- Cocoa Station (August 11, 2026) — The Federal Railroad Administration awarded the City of Cocoa approximately $57.5 million to design and build a new multimodal station on the Miami-to-Orlando corridor. OpCo will help construct it and then maintain and operate it.
- St. Lucie River Bridge (August 18, 2026) — The U.S. Department of Transportation ("USDOT") awarded the City of Stuart $78.9 million. Together with a $130 million USDOT grant committed in 2023 and $26.2 million of Company matching funds, it will replace the 100-year-old bridge, which carries both Brightline and FECR freight traffic, with a new double-track structure.
- Intrusion Mitigation Project — OpCo is upgrading 327 grade crossings between Miami and Cocoa and installing about 33 miles of corridor fencing under the federal RAISE grant program. As of August 31, 2026, 299 crossings were complete, and the fencing remains in preliminary design pending FECR approvals.
Development Projects and Other Assets
In addition to the Rail System, the Company holds interests in three development projects and a Las Vegas land joint venture.
- Commuter Access Rights — The planned commuter service would span up to 85 miles with at least 17 new stations along the Rail System's corridor through Miami-Dade, Broward and Palm Beach Counties. It is being developed through subsidiaries of Brightline Florida. OpCo granted the underlying Commuter Access Rights to the Commuter SPVs in 2022 and 2023.
- Tampa Assets — The planned Tampa extension would add an 84-mile segment from Orlando International Airport, with stops at the Orange County Convention Center, South International Drive and Tampa. The assets OpCo sold to Brightline Tampa in January 2024 (the "Tampa Assets") include design contracts, right-of-way lease awards, a $15.9 million federal grant and airport access rights.
- Brightline West — A planned 218-mile high-speed passenger rail line between Southern California and Las Vegas, still in the early phases of development. The project is held under non-Debtor BL West Holdings, in which Debtor Brightline Holdings owns approximately 40% and non-Brightline investment vehicles own the rest.
- Las Vegas Real Property — Debtor BL Florida owns approximately 40% of non-Debtor LV TOD Property Holdings LLC ("LV TOD JV"). LV TOD JV owns an approximately 90-acre property on the west side of Las Vegas Boulevard, between Warm Springs Road and Blue Diamond Road.
Workforce and Shared Services
Debtor Brightline Management employs about 520 people: roughly 90 in corporate functions, 340 in station, maintenance, engineering, safety, security and guest services roles, and 90 in train operations. About 100 are Transport Workers Union members and may become subject to a collective bargaining agreement now under negotiation. OpCo has no employees of its own and relies on Brightline Management under a management agreement, paying its costs plus a $500,000 annual fee. OpCo transferred about $45 million to Brightline Management in 2026, mainly for employee services and insurance. Brightline Management also manages non-Debtor Brightline Tampa under a separate agreement, for costs plus $25,000 a year.
A further 15 people are employed by two non-Debtor affiliates, BLH Capital & Management Services LLC and Brightline Train Development LLC (the "Non-Debtor Employers"). Under an employee sharing agreement, they work across the enterprise for Brightline Management, Debtor Brightline Holdings and non-Debtor DXE Management LLC. Together with Brightline Management's staff, they provide development, marketing, finance, legal, IT and administrative services to OpCo and Brightline Tampa.
Commuter Agreements
The three Commuter SPVs, MDC Commuter LLC, BRWD Commuter LLC and PBC Commuter LLC, rely on OpCo to develop their services. Under access agreements, OpCo is to let each affiliate run commuter trains on its county's segment of the Rail System and help it meet the conditions for launching service, including completing stations and infrastructure and obtaining regulatory approvals. Under development agreements, OpCo builds and manages construction of the commuter stations and track. Each affiliate pays OpCo $250,000 a year for this support, which Brightline Management's employees and the shared employees carry out.
Pending Litigation
- Virgin Enterprises — In a 2021 English suit brought by Virgin Enterprises Limited ("VEL"), the court held on October 12, 2023 that Brightline Holdings' 2020 termination of its 2018 Virgin trademark license was a repudiatory breach, and Brightline Holdings paid about $115.7 million. In December 2025, Brightline Holdings agreed to an $8.5 million settlement of VEL's further damages claim, guaranteed by Debtor FIHPNP. The settlement went unpaid, and VEL obtained an $8.6 million New York judgment against FIHPNP on August 5, 2026. VEL's motion for turnover of FIHPNP's interests in Debtor FIHP and non-Debtor FTL Garage LLC was pending at the Petition Date.
- Make-Whole Litigation — CK Opportunities Fund I ("CK Fund"), the majority lender under the Brightline Holdings Credit Facility, together with Knighthead- and Certares-affiliated funds, is suing Morgan Stanley, the facility's administrative agent, as well as certain Debtors and certain non-Debtors tied to Brightline West, for at least $750 million. The plaintiffs allege that a December 2022 preferred-equity issuance by BL West Holdings should have triggered the facility's make-whole. The Appellate Division allowed the plaintiffs to depose Fortress co-founder Wes Edens in March 2025. Summary-judgment motions were argued on September 3, 2026, and decision was reserved. CK Fund has since raised the same transaction in its objection to the DIP Facility, described below.
- Railroad Retirement Board — In May 2026, the Railroad Retirement Board found OpCo a covered employer effective February 8, 2019, the date of its first federal CRISI grant, potentially exposing it to unpaid contributions back to 2019. OpCo has sought reconsideration.
- FECR Commuter Dispute — FECR sued OpCo in July 2025, alleging that its commuter-rail talks with the counties breached the parties' joint use agreement. FECR later added Fortress as a defendant, and the suit was stayed in November 2025 pending arbitration.
- MiamiCentral Retail Foreclosure — In July 2026, the Tranche A lender under the BIH Retail Loan (see Non-Debtor Prepetition Obligations) sued to foreclose on the MiamiCentral Station retail property, alleging defaults on the $65 million Tranche A. A receiver was appointed in September 2026.
Debtor Prepetition Obligations
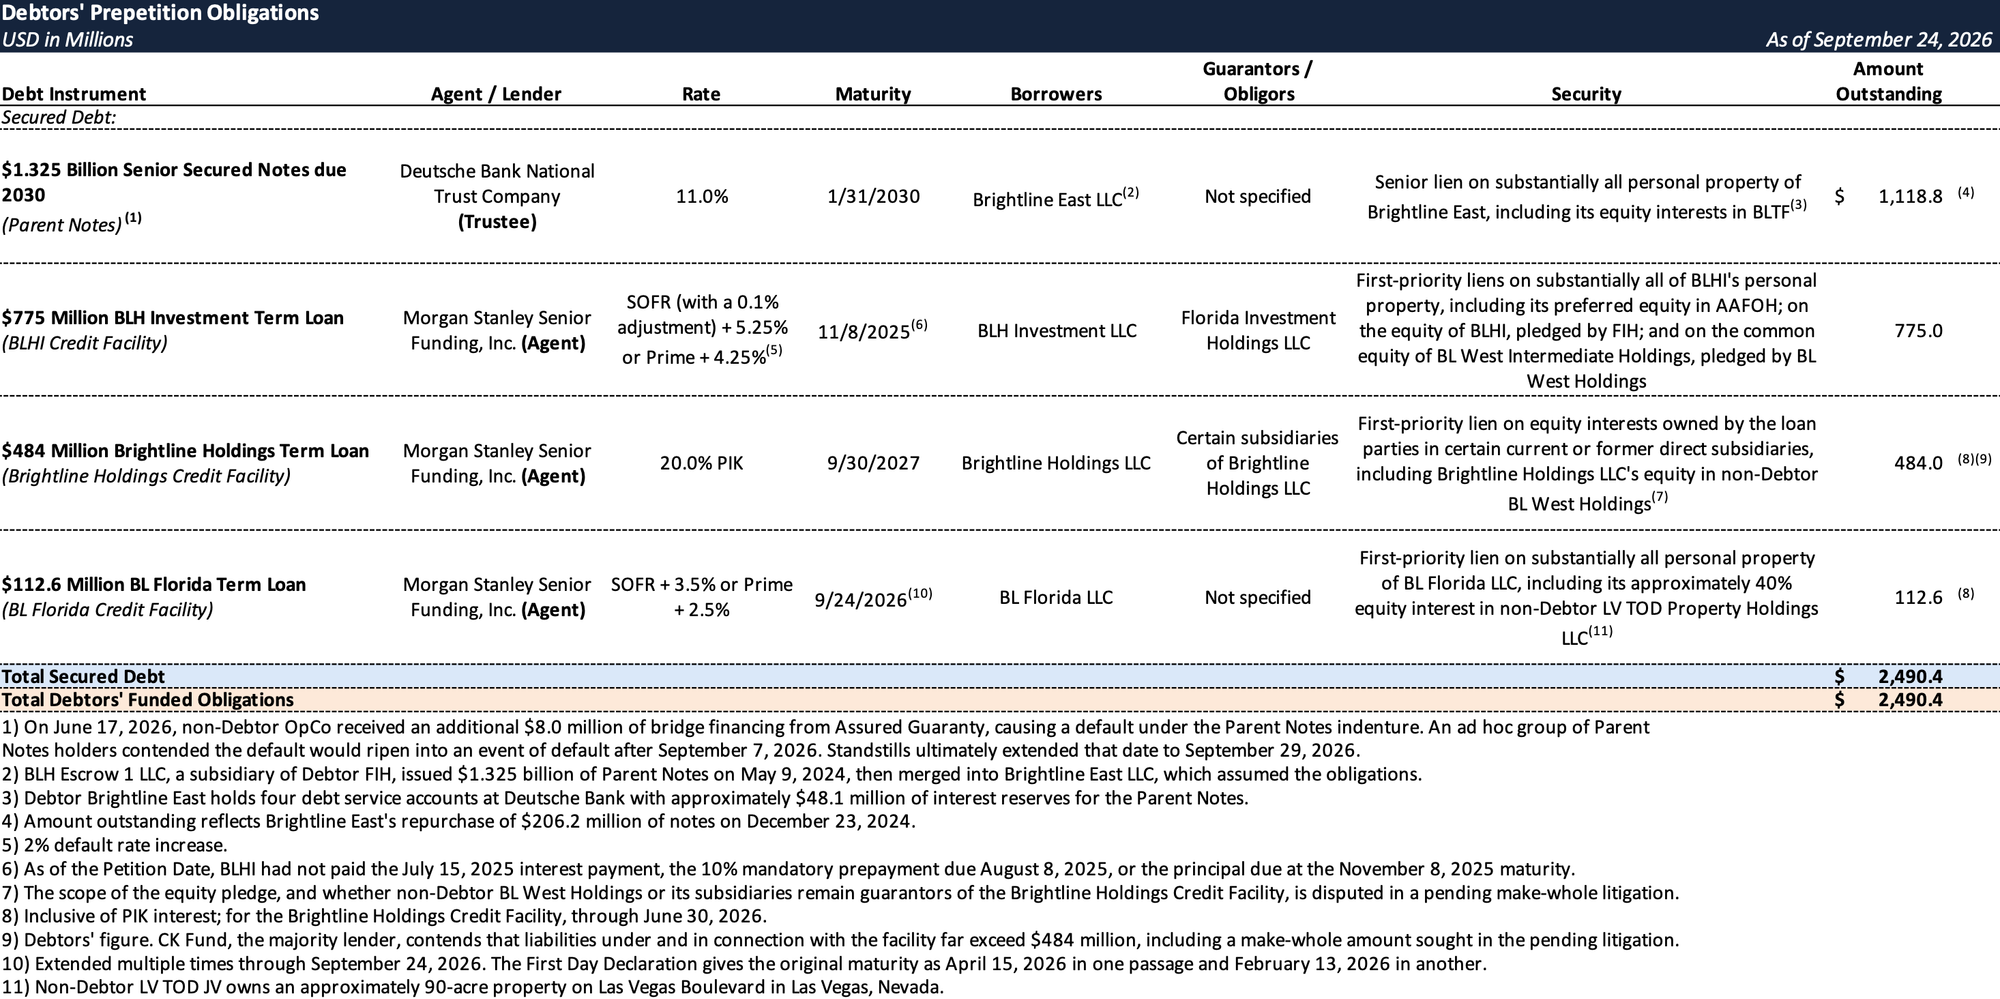
In addition to the prepetition funded debt listed in the table below, the Debtors have the following obligations.
- VEL Judgment — Debtor FIHPNP is subject to the $8.6 million VEL judgment described under Pending Litigation.
- OpCo Intercompany Loan — The organizational chart identifies Debtor FIHPNPNJ LLC as a credit party to an intercompany loan involving non-Debtor OpCo. The Debtors' board resolutions state that OpCo lent FIHPNPNJ $500,000 on September 18, 2026, with proceeds available to fund an account for administrative and legal expenses of the restructuring.
Creditor Group at Debtor Level
- Ad Hoc Group of East Noteholders — The Debtors use this name for a group of holders of the Parent Notes issued by Debtor Brightline East, represented by Davis Polk & Wardwell LLP. Bloomberg reported that the group is led by Redwood Capital, Aristeia Capital and Nut Tree Capital Management; in its court filings the group says it holds more than two-thirds of the notes. It is not a party to the Consensual RSA described below.
Non-Debtor Prepetition Obligations
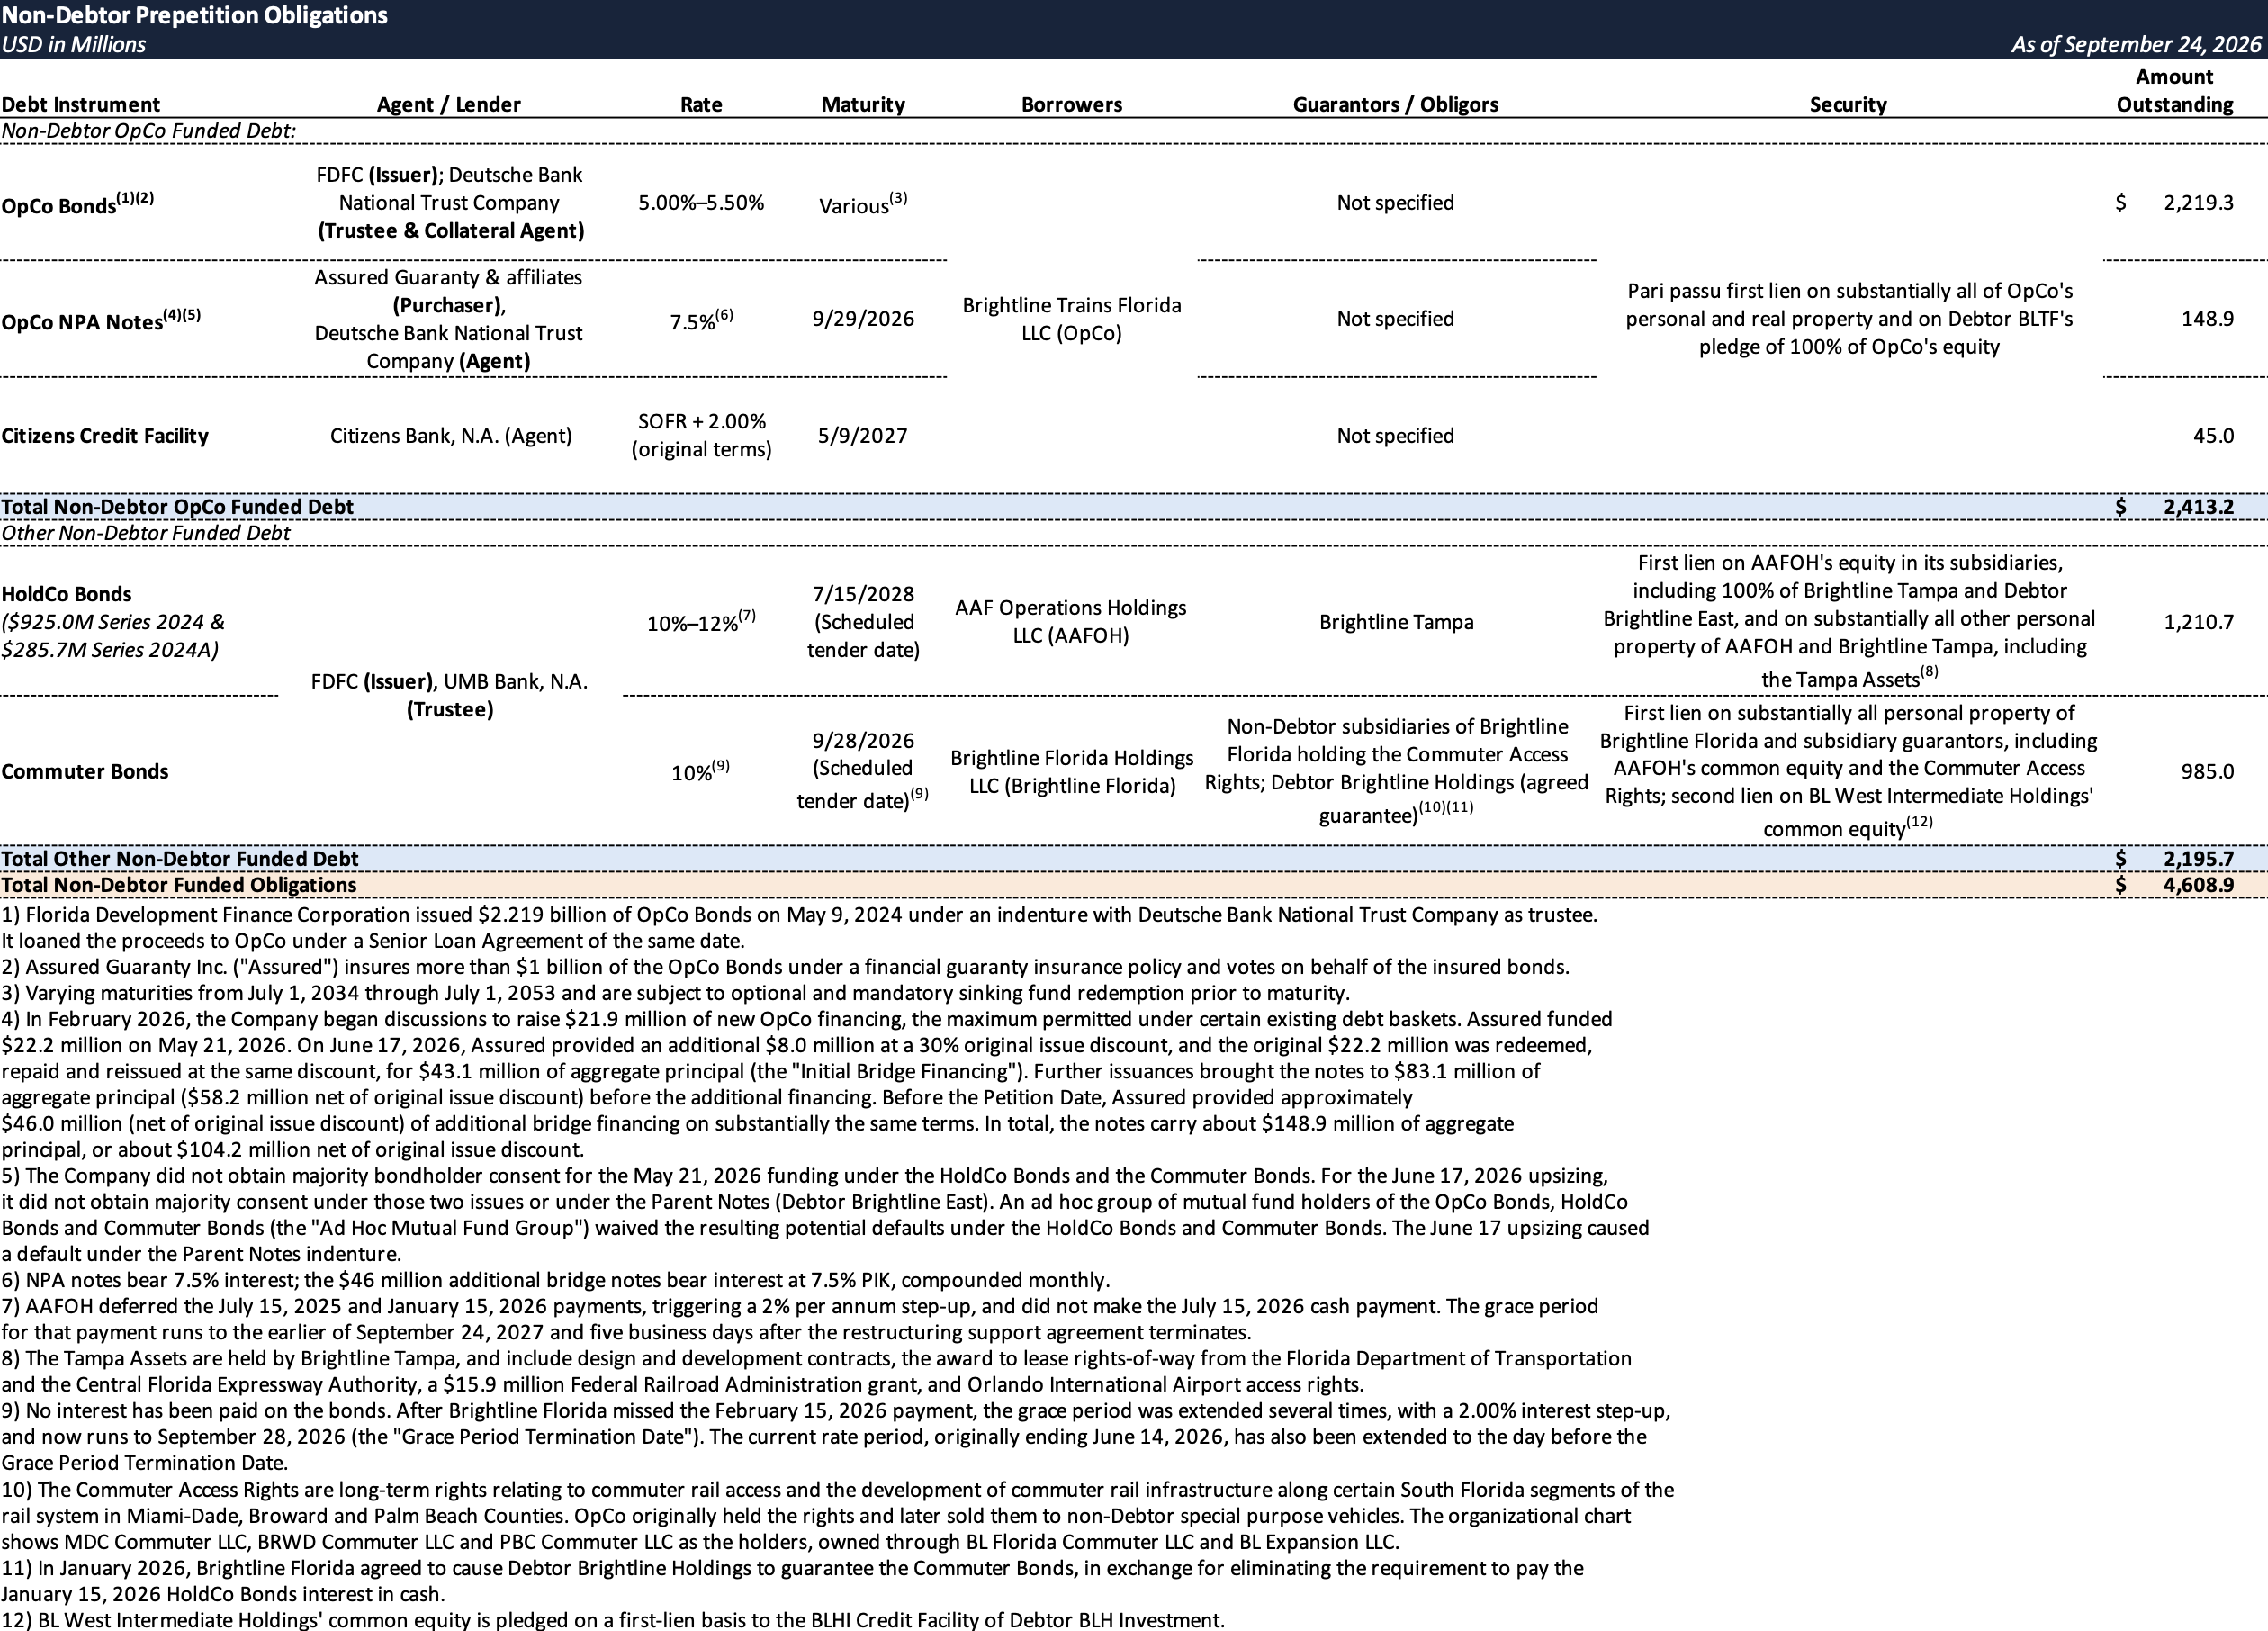
In addition to the prepetition funded debt listed in the table below, certain non-Debtor affiliates also have the following obligations, each of which includes a Debtor as a guarantor or credit party.
- BIH Retail Loan — Non-Debtor Brightline Investment Holdings LLC ("BIH") borrowed under a $128.5 million loan facility in 2022, consisting of a $65 million Tranche A and a $63.5 million Tranche B. Debtor FIH is parent guarantor and non-Debtor DTS DT Retail LLC ("DTS") is subsidiary guarantor. The loan is secured by BIH's equity in DTS and a mortgage on the MiamiCentral Station retail property owned by DTS, and is the subject of a pending foreclosure (see Pending Litigation).
- FECI Credit Agreement — The organizational chart shows an $18 million credit agreement for which non-Debtor Florida East Coast Industries LLC ("FECI") is the primary obligor and Debtor FIHP LLC is a member of the credit group.
- CanAm Loan — The organizational chart shows a $27.5 million loan for which Debtor FIHP LLC and non-Debtor FECI are credit parties.
Creditor Groups at Non-Debtor Level
- Assured — Assured Guaranty Inc. ("Assured") insures slightly over 50% of the OpCo Bonds and holds the majority debt voting position. Assured also holds the OpCo NPA Notes and is a party to the Consensual RSA described below.
- Ad Hoc Mutual Fund Group — The group consists of holders of the Commuter Bonds who also own a material portion of the HoldCo and OpCo Bonds. Bond Buyer has reported Nuveen, First Eagle, Invesco and Nomura as members. The group is represented by Herbert Smith Freehills Kramer and GLC Advisors.
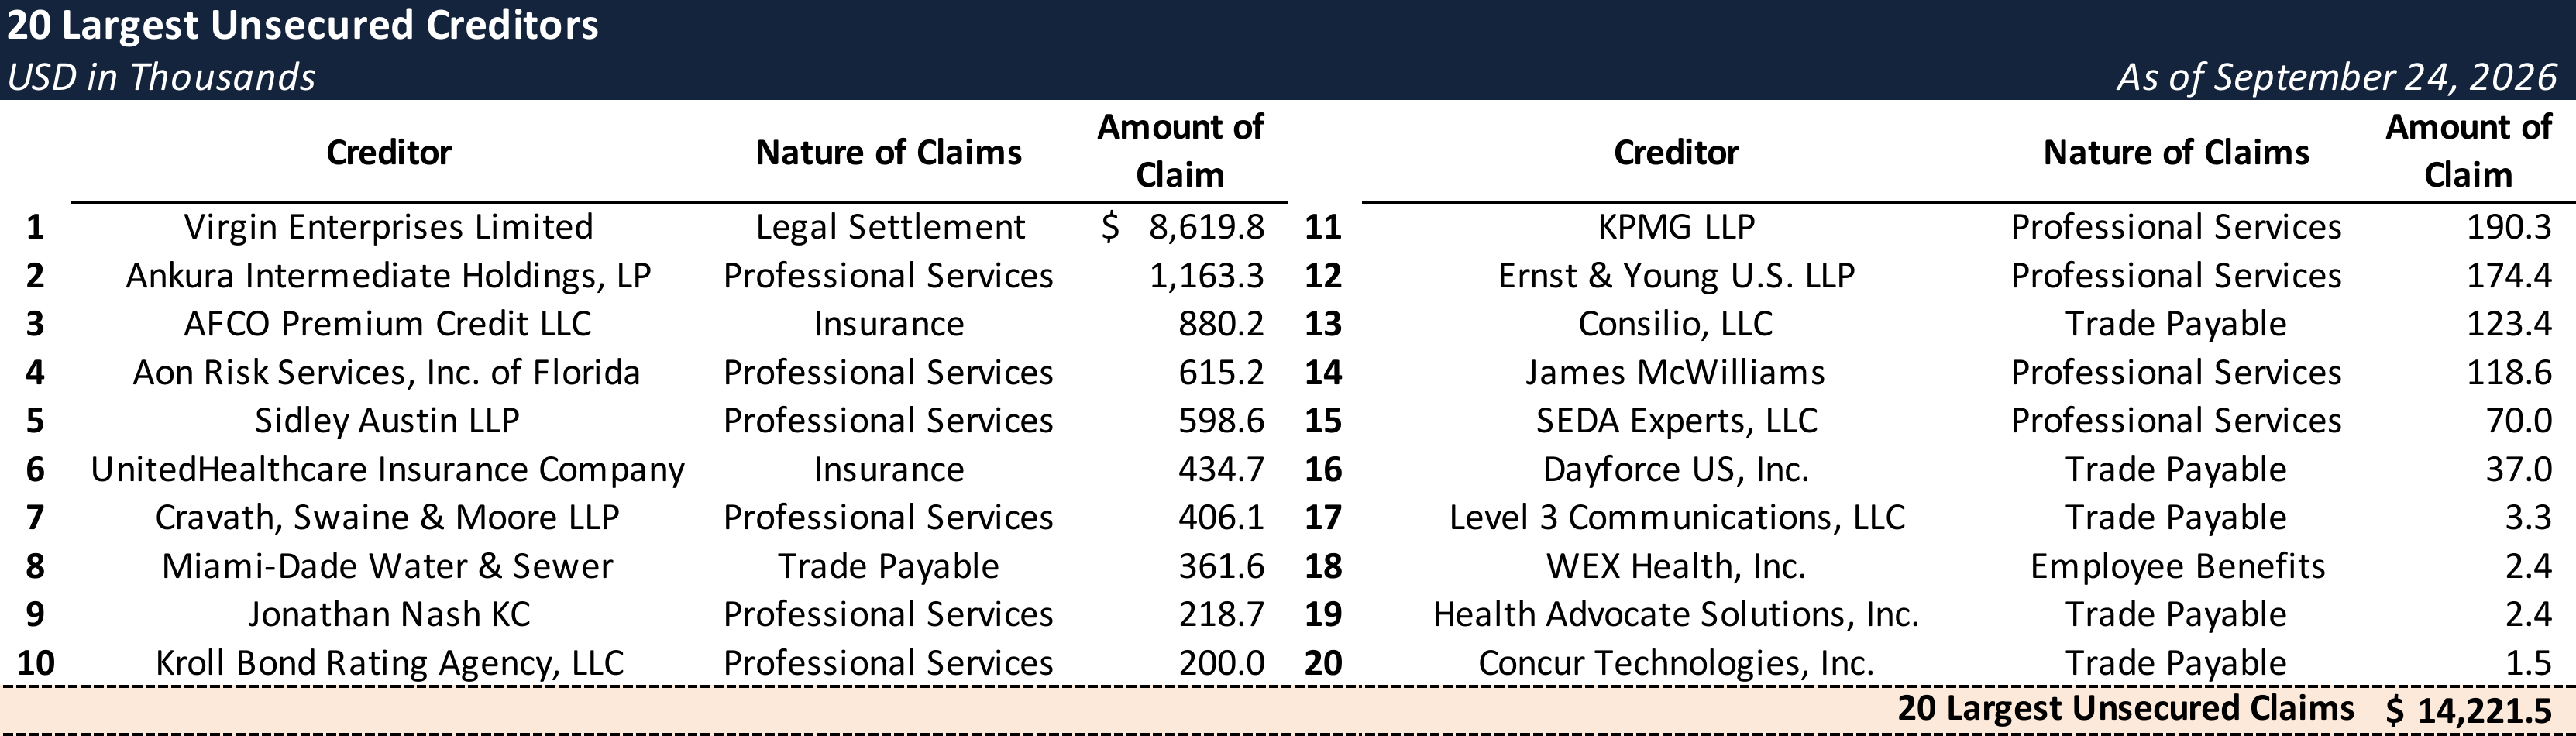
Top Unsecured Claims
Events Leading to Bankruptcy
Revenue Shortfall and Going Concern
Although ridership and revenue have grown year over year, both have lagged materially behind management's original projections, with total ridership and average fares each below expectations. As a result, OpCo, the only revenue-generating entity in the structure, has not generated enough cash to both pay its vendors and fund the distributions needed to service its own debt and that of its parent entities.
The 2025 results show the gap. OpCo grew total revenue 14% to $214 million as ridership rose 13% to 3.12 million trips, but it reported losses at every level of the income statement. Train operating expenses of $282.1 million, including $140.3 million of depreciation and amortization, produced a train operating loss of $68 million. After $59 million of corporate, general and administrative expenses, the operating loss was $127 million, compared with $153.5 million in 2024, and that figure already reflects $22.4 million of federal Restoration and Enhancement grant funds recorded as a reduction of operating expenses. After $114.6 million of net interest expense, OpCo reported a net loss of $233.1 million, against $2.19 billion of net long-term debt at year-end.
Cash flow was weaker still. Operating activities used $133.5 million, and OpCo spent another $93.3 million on capital expenditures. It covered the shortfall by drawing down $150.2 million of cash and restricted cash and fully drawing its $45 million Citizens revolver. Restricted cash fell to $136.9 million from $287.8 million. OpCo entered 2026 with $1.4 million of unrestricted cash and no revolver availability. Management disclosed that OpCo lacked the liquidity to meet its debt service and other obligations as they came due, and Ernst & Young's audit opinion included a going-concern paragraph.
The Debtors attribute the shortfall to several factors, including the suspension of service during the COVID-19 pandemic, slower-than-expected development of third-party travel distribution, cuts to marketing and sales spending during parts of 2025 because of liquidity constraints, and construction delays.
Restructuring Advisors Retention
Beginning in September 2025, Skadden, Arps, Slate, Meagher & Flom LLP advised the Company on its funded debt obligations, and later on strategic alternatives for upcoming maturities, certain litigation liabilities and negotiations with counterparties. During the first half of 2026, Perella Weinberg Partners LP and Houlihan Lokey Capital, Inc. were engaged as co-financial advisors, and Alvarez & Marsal North America, LLC was retained as restructuring advisor.
Failed Capital Raises and Sale Process
Beginning in 2025 and continuing into early 2026, the Company solicited equity investment in two waves of outreach to 32 infrastructure investors, transportation operators and financial sponsors. Ultimately, one party submitted a preliminary non-binding offer but declined to pursue a transaction. In May 2026, a broader sale process was launched covering all or part of the equity of OpCo or Debtor BLTF, OpCo's assets, the assets or equity of non-Debtor Brightline Tampa, and the equity of the Commuter SPVs, alone or in combination. However, this sale process also proved unsuccessful.
Separately, in the fourth quarter of 2025, the Company sought about $100 million of incremental capital to support OpCo's operations. It exchanged term sheets with the Ad Hoc Group of East Noteholders but could not obtain the consents needed to complete the transaction.
Liability Management Efforts
- Commuter Bonds Remarketing — Facing an August 13, 2025 mandatory tender on its $985 million of Series 2025A Commuter Bonds, non-Debtor Brightline Florida rolled them into new Series 2025B bonds. The remarketing was negotiated with the Ad Hoc Mutual Fund Group. As part of the remarketing, Brightline Florida agreed to cause non-Debtor AAFOH to pay the January 2026 HoldCo Bonds interest in cash and to provide a second lien on the BL West Intermediate Holdings common equity, which was granted on October 29, 2025.
- January 2026 HoldCo Bonds Interest — As the January 15, 2026 HoldCo Bonds interest date approached, the Ad Hoc Mutual Fund Group agreed to amend the Commuter Bonds indenture to remove the cash-payment requirement. In exchange, non-Debtor Brightline Florida agreed, among other things, to cause Debtor Brightline Holdings to guarantee the Series 2025B Commuter Bonds. The next HoldCo Bonds interest payment, due July 15, 2026, also went unpaid in cash, and its grace period has been extended to the earlier of September 24, 2027 and five business days after the Consensual RSA terminates, unless majority holders set another date.
- February 2026 Commuter Bonds Interest — Non-Debtor Brightline Florida then missed the February 15, 2026 interest payment on the Commuter Bonds. The Ad Hoc Mutual Fund Group agreed to extend the 10-business-day grace period to April 15, 2026, and further extensions pushed it to September 28, 2026.
- BL Florida Credit Facility Maturity Extension — Facing a February 13, 2026 maturity on the BL Florida Credit Facility, Debtor BL Florida negotiated several extensions with its lenders, ultimately to September 24, 2026, the Petition Date.
The OpCo Bridge Financing and the Parent Notes Default
From February 2026, the Company sought $21.9 million of new OpCo financing, the most its debt baskets allowed subject to certain consents, to fund critical vendor, employee and tax payments. On May 21, 2026, Assured funded $22.2 million of OpCo NPA Notes without the Company first obtaining majority consent under the HoldCo or Commuter Bonds, and the Ad Hoc Mutual Fund Group waived the potential default. On June 17, Assured added $8 million at a 30% original issue discount ("OID"), and the original $22.2 million was reissued at the same discount, bringing the notes to about $43.1 million. Assured will waive the OID if certain conditions in the Consensual RSA are met. The upsizing again proceeded without majority consent under the Parent Notes, HoldCo Bonds or Commuter Bonds.
The Ad Hoc Mutual Fund Group again waived the defaults under the HoldCo and Commuter Bonds, but the upsizing caused a default under the Parent Notes indenture, which the Ad Hoc Group of East Noteholders contended would ripen into an event of default after September 7. Standstill agreements entered on September 4 have since been extended through September 29. Before the filing, Assured also agreed to provide about $46 million of additional net proceeds to fund Chapter 11 preparation, payroll, critical vendors and working capital.
Chapter 11 Filing
The Consensual RSA
The Debtors filed with a restructuring support agreement dated September 24, 2026 (the "Consensual RSA") among the Company, Assured and the Ad Hoc Mutual Fund Group. A separate ad hoc group of OpCo bondholders represented by Cleary Gottlieb may join with the consent of the Company and the "Required Supporting Holders," defined as Assured together with members of the Ad Hoc Mutual Fund Group holding at least 75% of the group's commitments to purchase the exit notes.
The Consensual RSA contemplates three sets of transactions:
- OpCo Recapitalization — To be implemented through a Chapter 11 plan for BLTF, the Debtor that owns OpCo, which may be a joint plan with other Debtors, or, if the Required Supporting Holders elect, through a §363 sale of OpCo's equity.
- Separation — The HoldCo and Commuter entities, including non-Debtors AAFOH, Brightline Tampa and Brightline Florida and its commuter subsidiaries, are to be separated from the rest of the corporate structure, simultaneously with the OpCo recapitalization and without filing.
- Affiliate Plans — Creditors of the other Debtors are to be addressed through one or more affiliate plans, which may be the BLTF plan itself. The BLTF plan's effectiveness is not conditioned on any affiliate plan, and the affiliate transactions close only after, or together with, the OpCo recapitalization and the separation.
At exit, OpCo will issue $490 million of exit notes in two tranches, and a portion of the proceeds will refinance the DIP Facility described below. The first is $140 million of senior notes ranking equally with the OpCo Bonds, of which Assured will purchase or insure $70 million and the Ad Hoc Mutual Fund Group and other consenting OpCo bondholders will backstop and fund the remaining $70 million. The second is $350 million of second-lien junior notes to be purchased by the Ad Hoc Mutual Fund Group for a 10% payable-in-kind backstop fee, except for any portion that other consenting OpCo bondholders and Parent Notes holders elect to buy under an option to purchase an agreed amount. OpCo's equity will be contributed to a newly formed Delaware holding company ("New HoldCo"), and 95% of New HoldCo's equity will be distributed to the purchasers of the junior notes. The remaining 5% (the "Junior Stakeholder Pool") is reserved as consideration for certain Debtor-level creditors. Both portions are subject to dilution by a management incentive plan of up to 10%.
Creditors Treatment
The Consensual RSA provides the following treatment for creditors at the non-Debtor level:
- $2.219 billion OpCo Bonds — The bonds remain outstanding, and the Assured insurance policy on $1.133 billion of them remains in place. Supporting bondholders other than Assured agree to defer three coupons due through January 2028 until January 1, 2031, and insured bondholders who defer receive a new Assured policy guaranteeing repayment of the deferred interest by that date. If OpCo cannot pay non-deferred interest on the insured bonds, up to half of the shortfall may be funded with additional exit notes, one-third senior and two-thirds junior.
- $45 million Citizens Credit Facility — The parties will use commercially reasonable efforts to extend the facility's term.
- $1.2 billion HoldCo Bonds and $985 million Commuter Bonds — Both issues remain outstanding "with no reduction in aggregate principal amounts," per Brightline's announcement, and are to remain tax-exempt. Intercompany contracts between OpCo and the HoldCo and Commuter entities remain in place, but claims for past services under those contracts are released. The Commuter Bonds retain the second lien on BL West Intermediate Holdings' equity.
- $128.5 million BIH Retail Loan — Lenders to non-Debtor Brightline Investment Holdings, whose loan Debtor FIH guarantees, receive all of the equity in DTS DT Retail LLC and its MiamiCentral retail property, subject to the waterfall between the loan's two tranches.
Creditors of the Debtors receive cash, specific assets or retained collateral, together with a share of the Junior Stakeholder Pool:
- $1.1 billion Parent Notes — Holders receive approximately $48 million of cash in Debtor Brightline East's interest reserve accounts and at least half of the Junior Stakeholder Pool.
- $775 million BLHI Credit Facility — Lenders to Debtor BLH Investment retain their first lien on BL West Intermediate Holdings' equity and receive a share of the Junior Stakeholder Pool on account of BLH Investment's preferred equity in AAFOH.
- $484 million Brightline Holdings Credit Facility — Lenders to Debtor Brightline Holdings receive all of the equity of Brightline Holdings' pledged subsidiaries and a share of the Junior Stakeholder Pool.
- $112.6 million BL Florida Credit Facility — Lenders to Debtor BL Florida receive BL Florida's approximately 40% interest in the Las Vegas land joint venture and a share of the Junior Stakeholder Pool.
The DIP Facility
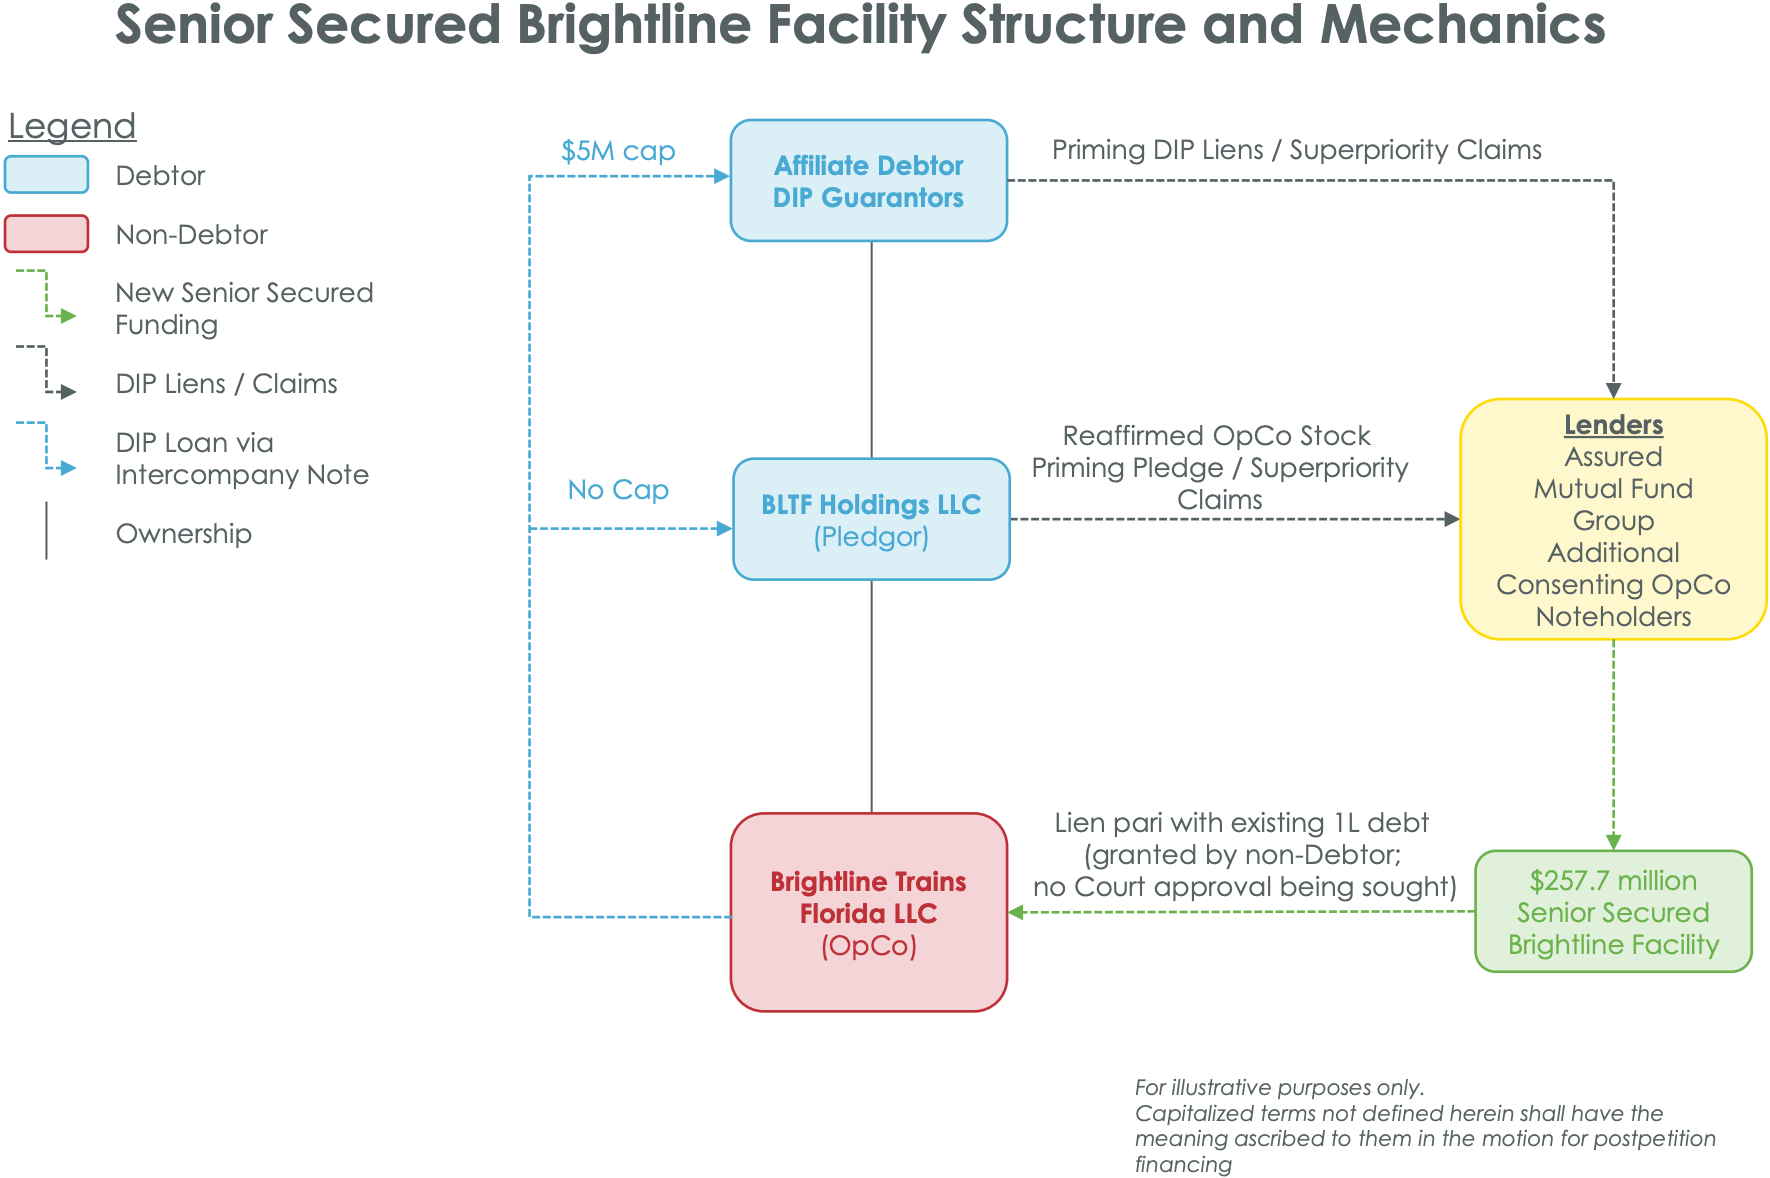
The Chapter 11 Cases will be funded through a $257.7 million senior secured note facility (the "DIP Facility"), of which $185.2 million would be available on entry of the interim order and the rest on entry of a final order. Non-Debtor OpCo is the borrower, and Deutsche Bank National Trust Company serves as administrative and collateral agent. Assured, the Ad Hoc Mutual Fund Group and other consenting OpCo bondholders purchase the notes ratably. Assured buys any allocation the other bondholders do not take up and has said it will provide up to $178 million. The other 16 Debtors are guarantors, but only to the extent they receive DIP proceeds through intercompany notes from OpCo, capped at $1.5 million per entity and $5 million in aggregate.
- Structure — The notes are secured by OpCo's own assets and by Debtor BLTF's reaffirmed pledge of 100% of OpCo's equity. Because OpCo is not a Debtor, the Debtors are not asking the Court to approve the loan to OpCo itself. Instead, they seek authority for BLTF to authorize the facility, approval of the priming lien on the pledged OpCo equity, and authorization of the intercompany loans that fund the cases.
- Pricing and Fees — Interest accrues at 10% PIK, rising by 2% during an event of default. Purchasers also earn an 8% commitment premium on their commitments, capitalized into principal at closing, plus a separate backstop premium that becomes fully earned on entry of the interim order.
- Maturity — The notes mature at the earliest of one year from the Petition Date (extendable by the requisite DIP purchasers), the effective date or substantial consummation of the BLTF plan, acceleration, or 45 days after the interim order if no final order has been entered.
- Events of Default — Events of default include cross-defaults on, and judgments over, $10 million; a change of control; failure to obtain a final order within 40 days; termination of the Consensual RSA or a missed milestone; and appointment of a trustee or examiner with expanded powers, other than a railroad trustee under §1163.
- Milestones — Entry of the final DIP order within 40 days of the interim order; filing of the plan and disclosure statement within 60 days of the Petition Date; a disclosure statement order within 105 days; confirmation within 45 days of the start of solicitation; and plan effectiveness within 14 days of confirmation. Assured may extend the effective-date deadline to 315 days after the Petition Date, or to 365 days with the consent of the Ad Hoc Mutual Fund Group.
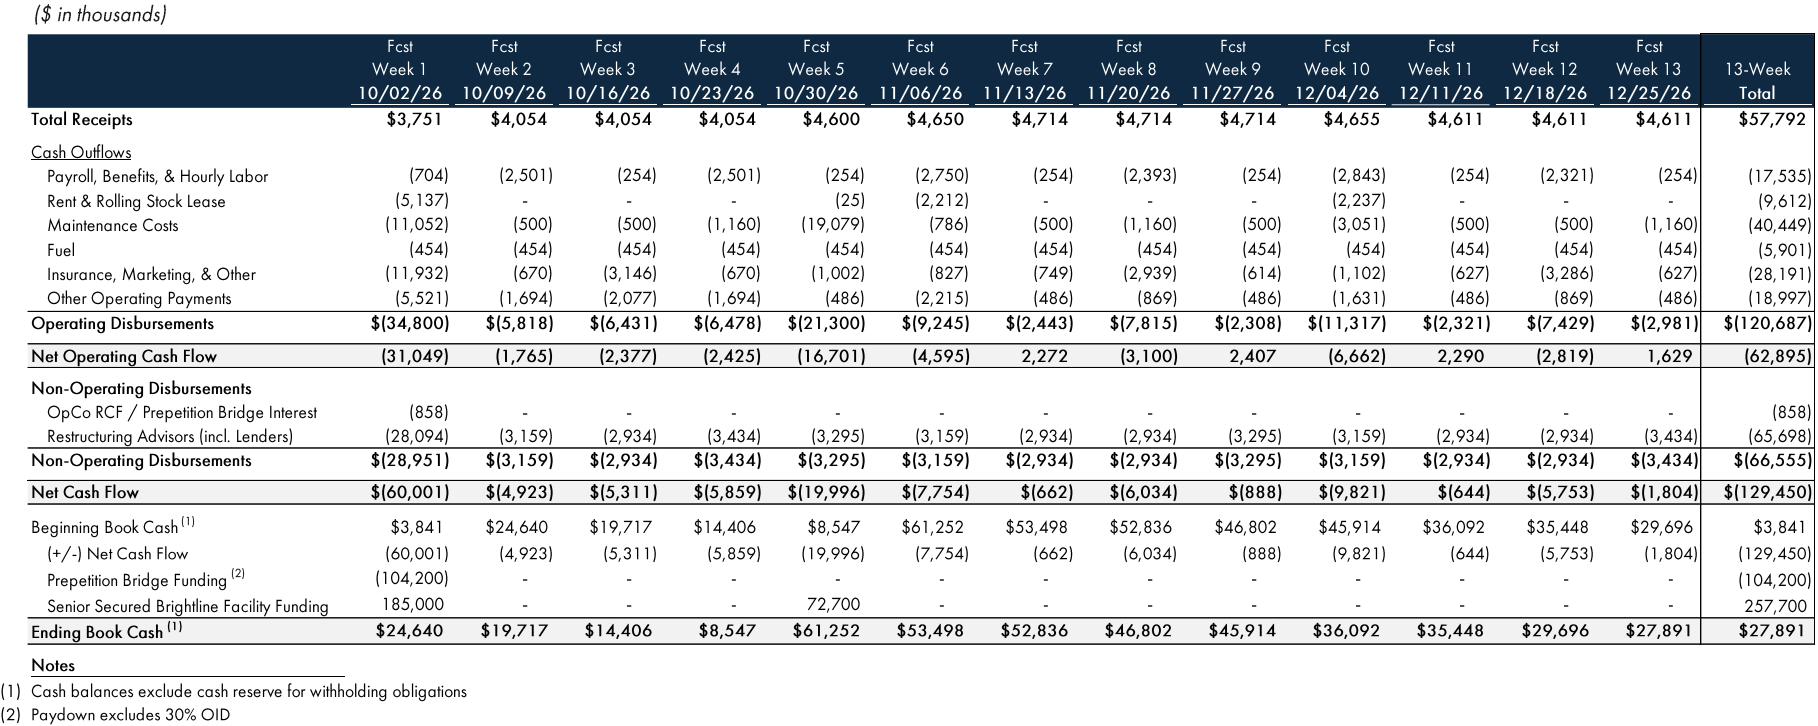
- Use of Proceeds — Proceeds may fund OpCo's and the Debtors' general corporate expenses, the costs of administering the Chapter 11 Cases and DIP fees, and will refinance the OpCo bridge notes. The initial budget provides for $104.2 million of OpCo NPA Notes, excluding OID, to be repaid in the first week.
- Priming — The DIP liens on the pledged OpCo equity would prime the existing pledge, which secures at least $2.413 billion of OpCo Bonds, Citizens Credit Facility loans and OpCo NPA Notes. The proposed interim order finds that holders of a majority of that debt have consented, or are deemed to have consented.
- Adequate Protection — The BLTF-level secured parties would receive replacement liens and §507(b) superpriority claims, both junior to the DIP liens and the carve-out. They would also receive current cash payment of Assured's insurance premiums, of non-default interest on the OpCo Bonds and Citizens loans, and of their advisors' fees. Secured creditors of the guarantor Debtors would receive replacement liens and §507(b) claims at the guarantor level.
- Carve-Out — The carve-out covers U.S. Trustee and clerk fees, OpCo's professional fees, and allowed estate professional fees, with post-trigger professional fees capped at $7.5 million. Affiliate Debtor amounts are subject to the same $1.5 million and $5 million caps.
- Stipulations and Challenge Period — BLTF would stipulate that the prepetition BLTF-level debt and liens are valid and unavoidable, that none of the secured parties controls or has controlled any Debtor, and that the estates hold no claims against them. Challenges are due 75 days after the interim order for BLTF, and 60 days after a creditors' committee is appointed for the other Debtors.
Initial Budget
CK Fund Objection
On September 27, 2026, CK Fund objected to the Debtors' first-day relief and demanded adequate protection. CK Fund bought $191.3 million of the Brightline Holdings Credit Facility's term loans from Morgan Stanley in September 2022. Seven Debtors guarantee the loans, which are secured by pledged equity in Brightline subsidiaries, including BL West Holdings.
The objection adds CK Fund's account of the December 2022 issuance at the center of the Make-Whole Litigation. According to CK Fund, BL West Holdings sold about 40% of its units for about $260 million to BL West Investment LLC, an entity controlled by Edens. CK Fund says the price was well below other valuations and that the deal handed BL West Investment control of the board. Brightline Holdings and Morgan Stanley then took the position that the Brightline West entities were no longer subsidiaries covered by the credit agreement, and released them as guarantors. CK Fund argues that this release allowed DesertXpress Enterprises, the BL West Holdings subsidiary developing Brightline West, to raise $2.5 billion of debt. Under the facility, that borrowing would otherwise have required a prepayment and triggered the make-whole.
CK Fund now characterizes the transaction as a fraudulent transfer that gave the estates valuable claims. It objects to the DIP Facility to the extent it would put liens on those claims, and opposes any good-faith finding for the DIP lenders, since the dispute has been litigated publicly for three years. CK Fund also refuses to consent to being primed. The lender argues that replacement liens and superpriority claims on the same collateral, ranking behind the DIP, do not adequately protect it without evidence of an equity cushion. As holder of more than half of the loans, CK Fund says Morgan Stanley has no authority to consent to the DIP terms on its behalf.
CK Fund also says the Debtors ignored its prepetition requests to discuss how its claims would be treated. It notes that under the Consensual RSA, the Brightline Holdings lenders would take ownership of Brightline Management, which employs the workforce that runs the Rail System. CK Fund reserves the right to seek a Chapter 11 trustee, relief from the automatic stay and standing to pursue estate claims.
Explore Bondoro Insights for live case dockets and comprehensive coverage of material filings from petition to plan confirmation.
Stay informed on every Chapter 11 bankruptcy case with liabilities exceeding $10 million. Subscribe for free to have our coverage delivered directly to your inbox, and explore our full archive of past summaries.
Subscribers can also opt in to timely filing alerts by updating their email preferences in Account Settings.


